
AI Tools for CFOs: Buy in the Order the Books Can Support
A CFO can choose finance AI more confidently by testing reconciliation, close, and forecasting in that order. Source traceability and reviewer capacity determine when to expand.
Published October 6, 2026
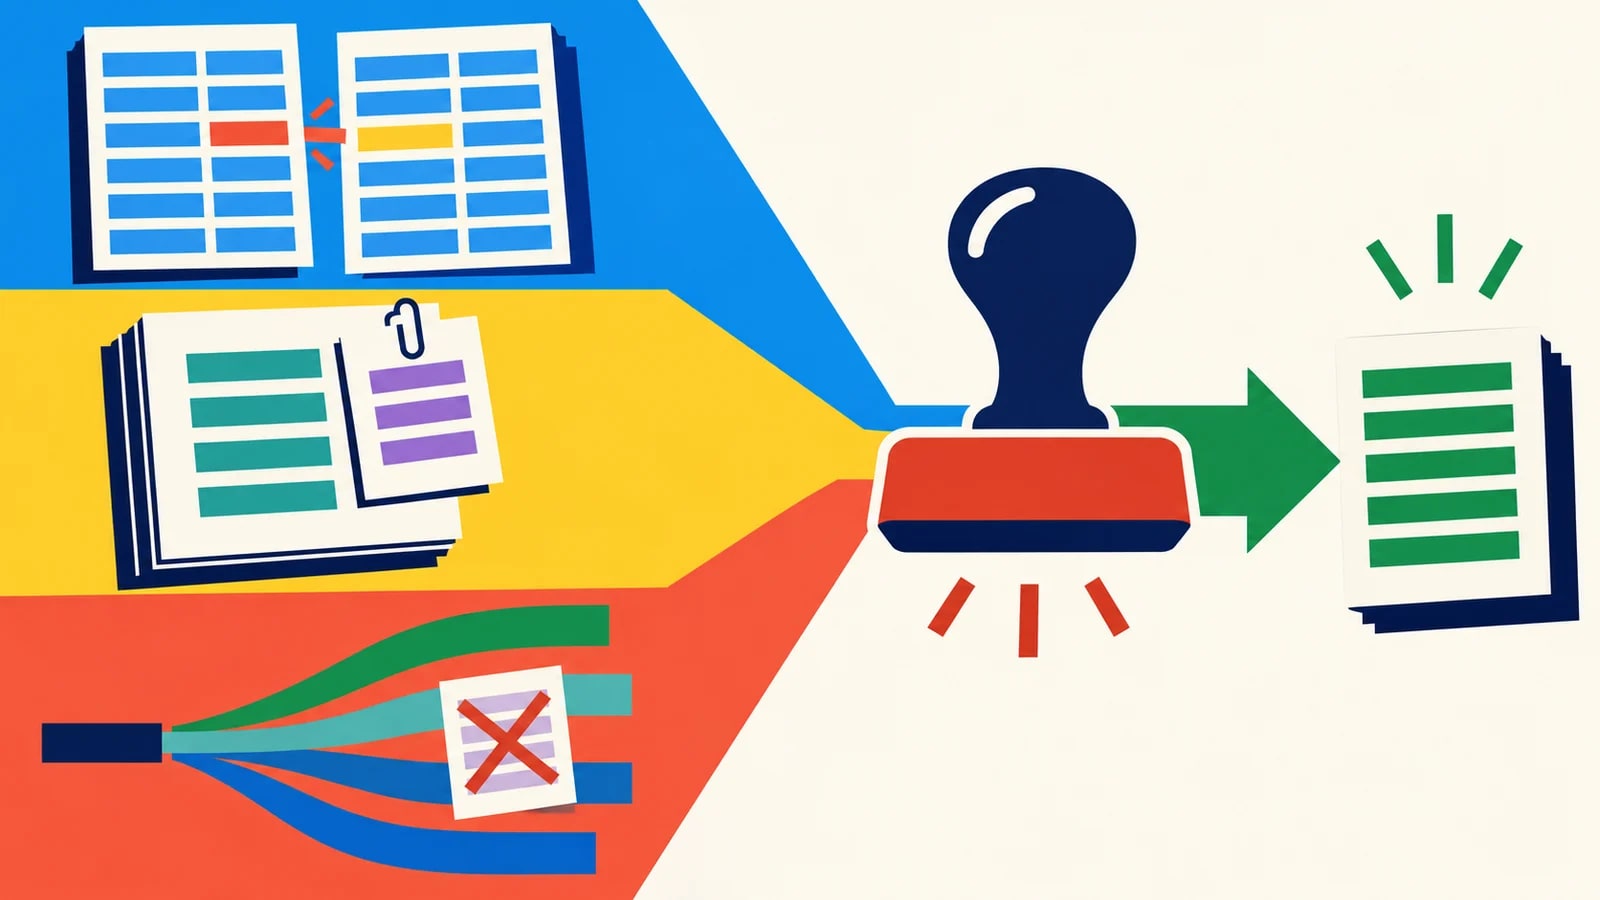
The office of the chief financial officer (CFO) has no shortage of AI features to buy. A better starting point is the sequence of evidence the finance team can defend. Can it reconcile source records? Can it explain a close item with a traceable path? Can it test a forecast against an agreed baseline? Buying a forecasting assistant while the underlying numbers are still disputed usually moves the argument into a shinier interface.
This guide is a purchasing order, not a ranking of finance vendors. Our earlier CFO automation overview describes the broad opportunities; this piece names the gates that should determine the next purchase.
First: test reconciliation where the truth is checkable
Reconciliation compares two sets of records and explains what matches and what does not. Microsoft’s Finance Agent documentation describes an Excel-based reconciliation tool that creates traceable identifiers linking results back to source tables. Its responsible-use FAQ warns that suggested matching rules require scrutiny and that Excel may change trailing digits in long numbers, producing false positives. Those are Microsoft’s descriptions and limitations. They make a good test question for any vendor: can a reviewer reproduce every match and investigate every exception?
Start with a period already closed and a pair of datasets whose differences the team knows. Blind the reviewer to the tool’s suggestions until the team has its own answer key. Count correct matches, missed differences, false matches, time to investigate, and the transactions that cannot be traced to source. A false match on a bank account or material amount is a stop condition even if most rows are right. The finance controller, not the vendor, owns the acceptance rule.
Second: improve the close packet, not just its prose
A close packet should connect a variance explanation to the ledger, policy, and person who approved the adjustment. Intuit’s 2026 Enterprise Suite release notes describe AI chat across connected entities and supporting context for answers. That is a provider feature claim, not proof that a specific company’s multi-entity close is controlled. Test whether the answer cites the right period, entity, account, and source record. If the explanation is fluent but its source path breaks, keep it as a draft.
An illustrative failure: the assistant writes “travel expense rose because of sales expansion,” but the ledger change is a late accrual reversal. A manager might accept the story because it sounds plausible. The reviewer must be able to point to the actual postings and correct the narrative before the board packet is sent. Record reviewer time and corrections along with drafting speed.
Third: use AI for forecast questions after the baseline works
Forecasting needs a plain baseline, named drivers, and a record of when assumptions changed. Let AI propose scenarios or summarize variance, but make it show which driver moved and which source supports that move. Compare the new workflow with the team’s current forecast on the same historical periods. A prettier explanation is not better if it cannot beat or usefully challenge the baseline. Separate forecast accuracy from the time spent preparing it.
Do not buy a new platform merely because it can answer a question in natural language. Microsoft’s Finance Agent overview describes access to enterprise resource planning data for accounts payable and receivable; availability and connected capabilities depend on deployment and licensing. Ask the administrator what is actually enabled in your environment. Compare that with the systems already paid for before adding another vendor.
The procurement shortlist should include the incumbent system and a no-new-tool option. For each candidate, ask what data is copied or connected, which account can take action, where an approval happens, and how the controller reconstructs a result six months later. A finance tool that creates a second unowned version of the ledger may add work even if the demonstration is faster. The buyer should demand a trace of one difficult transaction from source to reported answer.
A 30-day buying sequence
- Week 1: the controller selects one closed reconciliation and freezes a source-backed answer key.
- Week 2: test the candidate on matches and exceptions; stop if a material false match escapes review or source traceability fails.
- Week 3: run a close-packet draft on one account and record every unsupported explanation and reviewer minute.
- Week 4: only if the first two gates pass, test whether scenario work adds insight beyond the forecast baseline. Finance and security review data access and contract cost.
The approval memo should show license and integration costs, review work, errors, accepted outputs, and the specific operating action that uses any time released. Released hours are capacity; cash savings require a budget change. The business-case guide can hold the math, and the finance certification path can define who is qualified to sign off on the workflow.
When to wait
Wait when entities or account definitions disagree, reviewers cannot trace results to source, or the controller cannot name a failure that would stop use. Fix those conditions first. The CFO’s best early AI purchase may be a narrower reconciliation tool, a better source record, or no new tool this quarter.
Weekly Newsletter
AI Adoption Weekly
New research, field guides, training studies, and tool decisions for operators.
No spam. Unsubscribe anytime.
Related Comparisons
Calculator
AI seat cost calculator
List price × headcount. You enter the hours and the operating assumptions.